Buying Pre-Foreclosures and Auction Assets Safely in Orange County
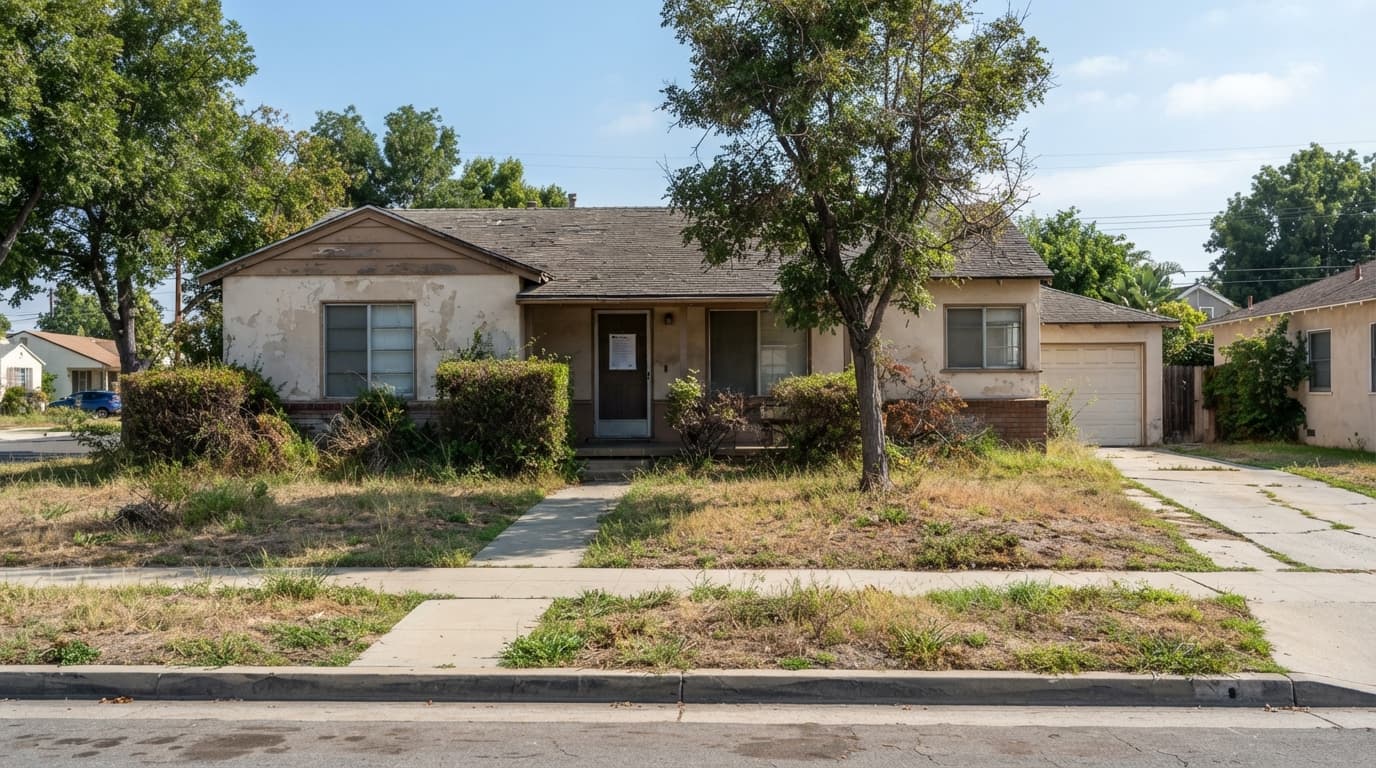
Pre-foreclosures and trustee sales can look like bargains, but they carry real title, lien, and liquidity risk. Learn how value-add investors in Orange County audit deals before bidding.
A discounted price on a courthouse-steps sale or a pre-foreclosure can look like instant equity. In practice, distressed buying is one of the highest-risk strategies in real estate, and the investors who do well treat it as a title and liquidity exercise first and a pricing exercise second. If you want to buy pre-foreclosure homes in Orange County, start by understanding what you are actually purchasing.
Pre-Foreclosure vs. Trustee Sale: Two Very Different Deals
A pre-foreclosure begins after a lender records a Notice of Default. The owner still holds title, which means you can negotiate directly, usually through a short sale or a conventional purchase. You get time for inspections, financing, and a proper title report, but you must deal with a stressed seller and often with lender approval.
A trustee sale is the final auction. The property is sold to the highest bidder, generally as-is, with no inspection contingency, no financing contingency, and little or no ability to walk the interior beforehand. Understanding trustee sale risks in California is not optional: you are buying with limited information and, in most cases, you must pay in certified funds on a very short clock.
Why Liens Decide Whether the Deal Works
Not every lien disappears at auction. The order of priority matters more than the opening bid.
- Senior liens (for example, a first mortgage when a junior lender is the one foreclosing) usually survive the sale. You can win the auction and inherit a loan balance.
- Junior liens recorded after the foreclosing lien are generally wiped out, but the details depend on recording order and the type of lien.
- Tax liens, HOA assessments, and recorded judgments may follow the property or carry special priority rules.
- Unrecorded issues, such as occupants or unpermitted work, never appear on a title report at all.
For example, a house with a $450,000 opening bid may look like a bargain next to a $900,000 market value. If a senior lien of $380,000 survives, your real cost basis starts at $830,000 before repairs, fees, and holding costs.
Run the Title Search Before You Raise a Hand
An auction property title search is the single most important step. Order a preliminary title report or a trustee sale guarantee from a title professional and read every exception. Our audit sequence looks like this:
- Pull the recorded Notice of Default and Notice of Trustee Sale and confirm which loan is being foreclosed.
- Order a title report and list every recorded lien, easement, and judgment with its recording date.
- Rank each lien by priority and total the amounts that would survive the sale.
- Check county records and permit history for open permits or unpermitted additions.
- Confirm occupancy status from the exterior and public records, and budget time and cost for a lawful eviction process if the property is occupied.
- Set a maximum bid that already includes surviving liens, repairs, and a margin of error.
Ask an attorney or title professional to review anything unclear. Trustee sales are generally final, and title insurance is typically not issued at the moment you buy.
Cash Liquidity Is a Hard Requirement
Auction buying generally requires cash or certified funds, available at or very shortly after the sale. Traditional mortgage financing does not fit this timeline, and a missed payment can mean losing the property and any deposit. Keep reserves beyond the bid for these items:
- Possible surviving liens and past-due taxes
- Repairs discovered only after you gain access
- Eviction or occupant-removal costs
- Insurance and carrying costs while you renovate
Many investors prefer the pre-foreclosure route precisely because it allows a title review and, in some cases, financing. As a dual-licensed broker and mortgage loan originator, we can pre-screen your funds and structure the purchase so the numbers are verified before you commit.
Avoiding Encumbered Auction Traps
Warning signs include surviving first mortgages, recent bankruptcies, a tangle of recorded judgments, and properties where nobody can explain who lives there. A low price does not compensate for a title problem you cannot cure. The safest rule is to pass on any deal where you cannot read the full title picture before bidding.
Your Next Step
If you are weighing a distressed purchase, bring the address, recorded notices, and your available liquidity, and request a Discreet Advisory Call. We will walk through lien priority, title findings, and a realistic maximum offer with you, privately and without pressure.
This article is for educational purposes only and is not legal, tax, or financial advice. Rates, programs, and rules change; verify current details before acting.
Troy Huynh, Broker DRE #01889229 | NMLS #344740, Global Estate Hub LLC
- #buy pre foreclosure homes Orange County
- #trustee sale risks California
- #auction property title search
- #senior vs junior liens
- #value-add investing
- #distressed property due diligence
Educational content only. This is not legal, tax, or financial advice and is not an offer or commitment to lend. All loans are subject to credit and underwriting approval. Equal Housing Opportunity.
Have a question about your own move or financing? Troy will follow up personally.
Discreet Advisory CallCompare loan options