Unlocking Net-Leased Assets & Commercial Up-Legs in Orange County
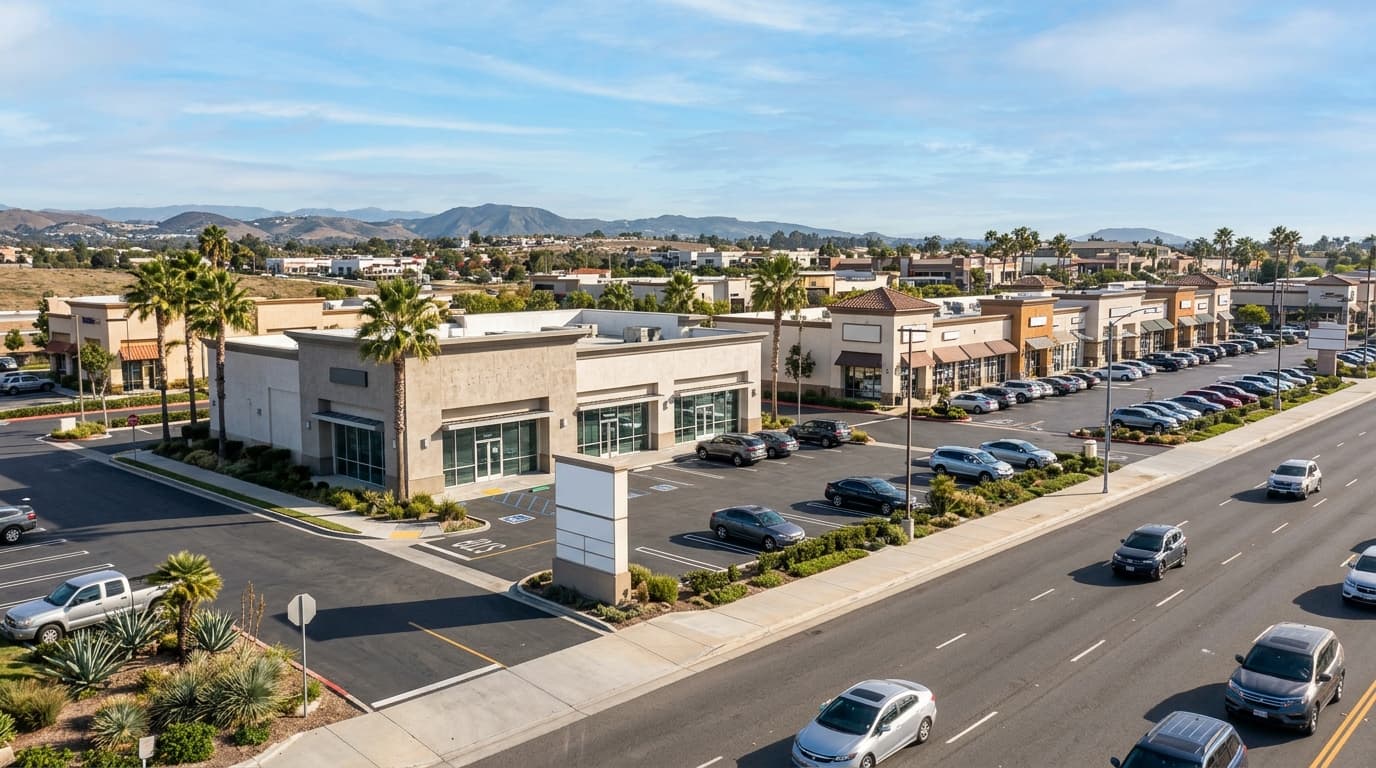
Understand single-tenant NNN lease investments, retail strip centers, and 5-10 year lease negotiation, plus how to think about capital placement and commercial up-leg properties in Orange County.
Commercial property rewards investors who read the lease as carefully as the listing. Net-leased assets can offer predictable income, but the details decide whether the income is truly steady. This guide explains commercial real estate in Orange County, how a NNN lease investment works, and what to know about a commercial property up leg.
What a NNN Lease Means
In a triple-net (NNN) lease, the tenant pays base rent plus the property's operating costs, typically property taxes, insurance, and common-area or building maintenance. The landlord's obligations are usually smaller than in a gross lease, which is why single-tenant NNN properties appeal to investors who want less day-to-day management.
Less management is not no risk. Lease language varies, and responsibility for the roof, structure, and parking lot is often negotiated. Always confirm which repairs stay with the landlord.
Two Common Property Types
- Single-tenant NNN: One tenant, one lease, and often a long term. Income depends heavily on that tenant's strength and the location's long-term appeal.
- Retail strip centers: Several tenants share one building and parking area. Vacancy in one space hurts less, but management, common-area costs, and tenant mix require more attention.
Neither is automatically better. Single-tenant deals concentrate risk, while multi-tenant centers spread it but demand more oversight.
Negotiating 5-10 Year Lease Terms
Lease terms commonly run from five to ten years in this segment. Longer terms can support stable income and a stronger resale story, but only if the tenant can actually pay for the whole term. Review these items:
- Rent escalations: fixed bumps or index-based increases over time.
- Renewal options: the number, length, and rent reset method.
- Guarantees: whether a corporate or personal guarantee backs the lease.
- Assignment and subletting: what the tenant may transfer without consent.
- Use clause and exclusives: what the tenant may sell and what competitors are barred.
Have a real estate attorney review every lease before you remove contingencies.
A Simple Return Check
Here is an illustrative example. Suppose a single-tenant building sells for $2,000,000 and the lease produces $120,000 of annual net operating income. The cap rate is 6.0% ($120,000 divided by $2,000,000). Now ask what happens if the tenant leaves: how long would re-leasing take, what would tenant improvements cost, and how would that change your return? The cap rate looks stable only if the answer is acceptable.
Capital Placement and the Up-Leg
Many investors buy net-leased assets as the replacement property in a 1031 exchange. The replacement property is often called the up-leg. In an exchange, strict deadlines and rules apply, including the use of a qualified intermediary, and your CPA and an exchange attorney should guide the tax side. Our role is to help you find, underwrite, and negotiate the property while the exchange professionals handle the legal structure.
Capital placement is also a question of balance. Consider your total holdings, your loan terms, and your need for liquidity. A strong lease on a property financed with an aggressive loan can still be a weak investment if the debt coverage is thin.
Due Diligence Checklist
Before you close, order a title report, review the tenant's financial statements where available, inspect the roof and parking surface, and confirm zoning and permitted use with the city. Request an environmental review where the prior use warrants it, such as a former gas station or dry cleaner. Check estoppel certificates, which confirm the lease terms directly with the tenant. These steps protect you from paying a premium price for an asset with hidden liabilities.
Next Step
If you are evaluating a net-leased building or planning a replacement purchase, schedule a commercial consultation with us. As a dual-licensed broker and mortgage loan originator, we can review the property, the lease, and the financing together so there are fewer surprises before you commit capital.
This article is for educational purposes only and is not legal, tax, or financial advice. Rates, programs, and rules change; verify current details before acting.
Troy Huynh, Broker DRE #01889229 | NMLS #344740, Global Estate Hub LLC
- #Commercial real estate Orange County
- #NNN lease investment
- #commercial property up leg
- #single-tenant NNN
- #retail strip centers
- #lease negotiation
- #capital placement
Educational content only. This is not legal, tax, or financial advice and is not an offer or commitment to lend. All loans are subject to credit and underwriting approval. Equal Housing Opportunity.
Have a question about your own move or financing? Troy will follow up personally.
Schedule Commercial ConsultationCompare loan options